Organizations need more than financial results to understand whether their strategies are working. Revenue, profitability, and cash flow show important aspects of performance, but they do not always explain customer outcomes, process efficiency, or the capabilities required for future success.
The Balanced Scorecard (BSC) is a strategic performance management framework that helps organizations translate strategy into objectives, performance measures, targets, and initiatives. It connects financial and nonfinancial indicators to provide a broader view of organizational performance.
The framework helps managers communicate strategic priorities, monitor progress, and assess how different areas of performance relate to one another. Its effectiveness depends on the quality of its design, the relevance of its indicators, and how consistently the organization uses it to guide decisions.
This article explains what the Balanced Scorecard is, how its four perspectives work, how to develop a strategy map, and how organizations can implement and manage a Balanced Scorecard system.
What Is the Balanced Scorecard?
The Balanced Scorecard is a strategic management and performance measurement framework that connects an organization’s strategy with measurable objectives and coordinated action. It combines financial measures with nonfinancial indicators to provide a broader assessment of performance.
Traditional performance reporting often places substantial emphasis on financial results. Although these indicators show what has happened financially, they may offer limited insight into the operational and organizational factors behind those results.
The Balanced Scorecard addresses this limitation by examining performance through four perspectives:
Financial: How should the organization perform financially?
Customer: How should the organization perform in the eyes of its customers?
Internal processes: Which internal processes must perform well?
Learning and growth: Which capabilities, skills, and organizational conditions support future performance?
These perspectives connect different aspects of organizational performance. For example, investments in employee capabilities may improve internal processes, which can contribute to better customer outcomes and, ultimately, stronger financial performance.
The Balanced Scorecard is therefore more than a dashboard or a collection of KPIs. It links strategic objectives, indicators, targets, and initiatives within a coordinated management system.
Why Is the Balanced Scorecard Important?
Organizations can collect extensive performance data and still struggle to determine whether their activities support strategic priorities. Departments may track different indicators, managers may interpret objectives differently, and operational initiatives may proceed without a clear connection to the overall strategy.
The Balanced Scorecard provides a structure for addressing these challenges.
1. Connect strategy with performance measurement
The framework translates broad strategic priorities into explicit objectives and measurable results. This connection helps managers identify what the organization needs to achieve and how progress will be assessed.
2. Provide a broader view of performance
Financial results remain important, but they represent only one perspective. Customer outcomes, internal processes, and organizational capabilities can help explain the conditions that contribute to financial performance over time.
3. Improve strategic alignment
A Balanced Scorecard can help departments and business units connect their objectives to organizational priorities. This alignment requires clear communication and careful consideration of what each unit can influence.
4. Support communication and accountability
A structured scorecard clarifies objectives, indicators, targets, responsibilities, and reporting expectations. Managers can use it to discuss results and determine which actions require attention.
5. Support strategy review and recalibration
Performance results can reveal gaps between expected and actual outcomes. Organizations can investigate these gaps, review their assumptions, and revise objectives or initiatives when circumstances or strategic priorities change.
Research supports the importance of implementation quality. A 2022 systematic literature review by Kumar, Prince, and Baker examined 114 Balanced Scorecard articles published between 1992 and 2021. The authors highlighted management support, communication, coordination, and relationships among the four perspectives as relevant implementation considerations. Read the academic review of Balanced Scorecard research.
What Are the Four Balanced Scorecard Perspectives?
The four perspectives provide different but connected views of organizational performance. The indicators within each perspective should reflect the organization’s strategy rather than follow a universal list.
1. Financial perspective
The financial perspective examines whether the organization’s strategy supports its financial objectives. Relevant measures depend on the organization’s business model, ownership structure, and strategic priorities.
Common examples include:
Return on investment (ROI)
Revenue growth
Cash flow
Profitability
Operating costs
A commercial organization may prioritize profitability and revenue growth, while a public or nonprofit organization may place greater emphasis on budget utilization, financial sustainability, or responsible resource allocation.
Financial indicators show important results, but managers should also examine the operational and customer-related factors that contribute to those results.
2. Customer perspective
The customer perspective examines how the organization intends to create and maintain relationships with its customers or service users.
Possible indicators include:
Customer satisfaction rate
Customer retention rate
Customer complaints
Market share
Customer acquisition or conversion rate
For example, a company that prioritizes customer retention may monitor satisfaction, repeat purchases, and service quality. A public service organization may assess service-user satisfaction, accessibility, or the timeliness of service delivery.
The selected measures should reflect the customer outcomes that matter most to the strategy.
3. Internal processes perspective
The internal processes perspective focuses on the operational activities that contribute to customer and financial outcomes. It helps organizations identify which processes require improvement or closer monitoring.
Potential indicators include:
Process cycle time
Error or defect rate
Service delivery time
Process automation rate
Resource utilization
Compliance with process standards
An organization that seeks to improve service delivery, for instance, may monitor turnaround time, process errors, and the proportion of cases completed within the required period.
The relevant processes depend on the organization’s strategic priorities. Measuring every operational activity can produce an unwieldy scorecard, so selection should focus on processes with a clear relationship to strategic objectives.
4. Learning and growth perspective
The learning and growth perspective examines the capabilities and organizational conditions that support current and future performance. It often includes employee skills, organizational culture, information systems, and the capacity to improve.
Possible indicators include:
Employee engagement or job satisfaction
Employee turnover
Training participation
Competency assessment results
Access to relevant information systems
Progress in developing critical capabilities
For example, an organization that plans to automate important processes may need employees with appropriate digital skills, reliable information systems, and a culture that supports learning.
These measures help managers assess whether the organization is developing the capabilities required to deliver its strategy over time.
How Does the Balanced Scorecard Work?
A Balanced Scorecard system connects strategic direction with objectives, performance measures, and initiatives. The components work together rather than operate as separate reporting tools.
A typical architecture includes the following elements:
Component
Purpose
Key question
Desired state of evolution
Defines the organization’s intended direction through its mission, vision, values, and goals
Where does the organization want to go?
Strategy map
Organizes strategic objectives and shows their proposed cause-and-effect relationships across the four perspectives
What must the organization achieve, and how are the objectives connected?
Performance scorecard
Connects objectives to KPIs, targets, and thresholds
How will progress be measured?
Dashboard
Presents performance information for monitoring and review
What do the results show?
Portfolio of initiatives
Organizes the projects and actions intended to achieve strategic objectives
What will the organization do to achieve its objectives?
These components support different stages of strategic management. The strategy map communicates the logic of the strategy, the scorecard specifies how performance will be measured, the dashboard presents results, and the initiative portfolio tracks the work intended to produce the desired outcomes.
What Is a Balanced Scorecard Strategy Map?
A Balanced Scorecard strategy map is a visual representation of an organization’s strategic objectives and the relationships proposed between them. It helps explain how objectives across the four perspectives contribute to the overall strategy.
Consider an airline that wants to improve profitability while maintaining high safety standards.
Its strategy map might connect objectives as follows:
Learning and growth: Develop employee skills and strengthen the safety culture.
Internal processes: Reduce turnaround time, improve resource utilization, and maintain safety standards.
Customer: Improve on-time performance and offer competitive pricing.
Financial: Increase revenue and profitability while managing operating costs.
The logic is that stronger employee capabilities and safety practices may support more reliable operations. Better operations may improve the customer experience and support financial objectives.
These connections represent strategic hypotheses that management should assess through performance data and operational evidence. A strategy map does not prove that one objective will automatically cause another. Its purpose is to make the proposed relationships explicit so they can be discussed, tested, and revised.
How to Implement a Balanced Scorecard
A Balanced Scorecard implementation requires more than creating a strategy map and choosing indicators. Organizations need to establish a clear strategic direction, assign responsibilities, and integrate the framework into their management routines.
Step 1: Assess the organization’s current position
Review the existing strategy, performance management practices, organizational structure, data availability, and stakeholder expectations.
The assessment should identify current strengths, measurement gaps, governance issues, and areas where departments lack a shared understanding of strategic priorities.
Step 2: Clarify strategy and organizational objectives
Define the organization’s desired direction, including its mission, vision, values, goals, and strategic priorities.
Objectives should describe what the organization intends to achieve. They should be clear enough to guide performance measurement and decision-making.
Step 3: Develop the strategy map
Arrange the objectives across the four perspectives and identify the proposed relationships among them.
Review whether the objectives collectively support the strategy, whether important dependencies are represented, and whether the proposed cause-and-effect relationships are reasonable.
Step 4: Select KPIs and define targets
Choose indicators that measure progress toward the objectives. For each KPI, establish a clear definition, calculation method, data source, reporting frequency, and responsible owner.
Targets should reflect strategic expectations, historical performance, available resources, and relevant external or internal evidence. Thresholds can help identify when results require attention.
Avoid selecting indicators solely because data is readily available. The KPI must measure something relevant to the objective.
Step 5: Identify and prioritize initiatives
Determine which projects, programs, or activities are required to achieve the objectives. Assign initiative owners and establish milestones, budgets, timelines, and progress measures where appropriate.
Initiatives should have a clear connection to strategic objectives. A long list of projects does not necessarily represent a coherent strategy execution plan.
Step 6: Align objectives across organizational levels
Translate organizational priorities into relevant objectives for business units, departments, and teams. This process is often described as alignment and cascading.
Cascading should preserve the connection to organizational strategy while accounting for the responsibilities and influence of each unit. Measures should not assign accountability for outcomes that a team cannot reasonably control.
Step 7: Monitor performance and recalibrate
Review KPI results and initiative progress at appropriate intervals. Investigate deviations, discuss their causes, and determine whether corrective action is required.
The organization may need to revise initiatives, adjust resource allocation, improve measurement practices, or reconsider strategic assumptions. Changes should follow a clear governance process so the scorecard remains consistent and useful.
What Is the Difference Between a Balanced Scorecard, a KPI Dashboard, and a Strategy Map?
These terms are related, but they describe different components or tools.
Tool
Primary purpose
Typical contents
Balanced Scorecard
Connects strategy, objectives, performance measures, targets, and initiatives
Strategic objectives, KPIs, targets, and linked management activities
KPI dashboard
Presents performance data for monitoring
KPI results, trends, status indicators, and visual summaries
Strategy map
Communicates strategic objectives and their proposed relationships
Objectives arranged across the four perspectives, with cause-and-effect links
A dashboard can display the results of selected KPIs without showing how those indicators relate to the strategy. A strategy map can communicate strategic logic without providing the detailed performance results found in a dashboard.
The Balanced Scorecard brings these elements together within a broader performance management system. The specific architecture varies by organization, but the essential purpose is to connect strategic intent with measurable performance and action.
Common Balanced Scorecard Implementation Challenges
Organizations can encounter several difficulties when designing or implementing a Balanced Scorecard.
Too many KPIs
A scorecard with excessive indicators can make it difficult to identify the measures that matter most. Select KPIs based on their relevance to strategic objectives and their usefulness in management decisions.
Weak links between objectives and measures
An indicator may be easy to measure but still fail to represent the intended objective. Each KPI should have a clear rationale and a documented relationship to the objective it measures.
Limited leadership support
Implementation can lose momentum when leaders do not communicate the purpose of the system, participate in reviews, or use performance information to guide decisions.
Poor data quality and inconsistent definitions
Different departments may calculate the same KPI in different ways or rely on data sources with inconsistent quality. Standard definitions, documented calculation rules, and clear ownership help address this problem.
Limited employee involvement
A scorecard designed entirely by senior management may overlook operational realities or assign responsibility for outcomes that employees cannot influence. Consultation with relevant stakeholders can improve the quality and practical relevance of the framework.
Treating the scorecard as a reporting exercise
A scorecard that produces reports without influencing decisions can become an administrative burden. Performance reviews should examine the meaning of results, the status of initiatives, and the actions required to address gaps.
A systematic literature review by Lueg and Vu examined empirical research on Balanced Scorecard implementation. Their findings highlighted the importance of design quality, individual and organizational factors, leadership, and organizational culture. The review also cautioned against treating implementation speed as the only measure of implementation success. Read the research on Balanced Scorecard implementation success factors.
How Can Organizations Assess Balanced Scorecard Effectiveness?
The effectiveness of a Balanced Scorecard should not be judged solely by whether the organization has completed a scorecard document or dashboard. The more important question is whether the framework supports strategic management and performance review.
Organizations can assess their approach by asking:
Are strategic objectives clearly defined and understood?
Do the four perspectives reflect the organization’s strategy?
Are the relationships between objectives explicit and credible?
Do the KPIs measure progress toward the objectives?
Are targets, thresholds, data sources, and responsibilities documented?
Do initiatives have clear owners, budgets, and milestones?
Do departments understand how their objectives connect to organizational priorities?
Are performance reviews followed by decisions or actions?
Does the organization revise its assumptions and measures when evidence indicates a need for change?
These questions can help identify gaps in the framework’s design and use. An assessment should consider the organization’s context, strategic maturity, governance arrangements, and the quality of available performance information.
Frequently Asked Questions About the Balanced Scorecard
What is the main purpose of the Balanced Scorecard?
The main purpose of the Balanced Scorecard is to connect organizational strategy with measurable objectives, performance indicators, targets, and initiatives. It provides a structured view of financial and nonfinancial performance and supports strategic communication, monitoring, and review.
What are the four perspectives of the Balanced Scorecard?
The four perspectives are financial, customer, internal processes, and learning and growth. Together, they help organizations assess financial results, customer outcomes, operational performance, and the capabilities required for future success.
What is the difference between a KPI and a Balanced Scorecard?
A KPI is a measure used to assess performance in relation to an objective or expected result. The Balanced Scorecard is a broader framework that connects strategic objectives with KPIs, targets, and initiatives across the four perspectives.
What is a Balanced Scorecard strategy map?
A strategy map is a visual representation of strategic objectives and their proposed cause-and-effect relationships across the four perspectives. It helps communicate how different objectives contribute to the organization’s overall strategy.
Is the Balanced Scorecard suitable for public-sector organizations?
Yes. Public-sector organizations can adapt the Balanced Scorecard to their mandates, stakeholder requirements, and intended outcomes. They may place greater emphasis on service delivery, public outcomes, accountability, and resource stewardship than on profitability.
What are the main components of a Balanced Scorecard management system?
A Balanced Scorecard management system can include a desired state of evolution, strategy map, performance scorecard, dashboard, and portfolio of initiatives. Supporting documentation may include KPI definitions, KPI trend analyses, initiative descriptions, and project status reports.
How often should a Balanced Scorecard be reviewed?
Review frequency depends on the organization’s operating context, the indicators being monitored, and the speed at which relevant conditions change. Operational indicators may require frequent monitoring, while strategic reviews may occur monthly, quarterly, or at another interval suited to the organization’s governance process.
If you’re ready to put the Balanced Scorecard into practice, enroll in The KPI Institute’s Certified Balanced Scorecard Management System Professional course. Explore the practical application, test your knowledge, and strengthen your ability to design and manage a Balanced Scorecard system.
*********
Editor’s Note: This article is based on the learning content of The KPI Institute’s Certified Balanced Scorecard Management System Professional course, which explores the principles, components, and practices involved in developing and managing a Balanced Scorecard system.
A Key Performance Indicator (KPI) is a measurable expression of the achievement of a desired level of results in an area relevant to the evaluated entity’s activity. This is the definition used by The KPI Institute, a global research, training, and consultancy organization with more than 22 years of experience in performance management.
In practical terms, a KPI is a measure used to evaluate progress toward an important organizational, departmental, team, or individual objective. A KPI is not simply any number an organization can track; it is a measure selected for its relevance to a desired result and its usefulness in evaluating and improving performance.
This guide examines:
What makes a measure a KPI and how the concept is defined within The KPI Institute’s performance management framework
How KPIs differ from metrics, measures, Performance Indicators (PIs), and Key Risk Indicators (KRIs)
How KPIs operate at corporate, departmental, team, and individual levels and connect performance to organizational objectives
Why KPIs matter for clarity, focus, improvement, engagement, communication, and organizational learning
The different types of KPIs, including leading and lagging indicators, strategic and operational KPIs, and count, percentage, and monetary measures
How KPIs fit within the Balanced Scorecard and its four perspectives for measuring and managing organizational performance
How to formulate a good KPI, from defining the objective to applying SMART criteria
How the KPI lifecycle works, including the establishment, use, review, and evolution of KPIs
Practical KPI examples by department, covering finance, human resources, sales and marketing, operations, and IT and service management
Common KPI mistakes and the performance management practices that can help organizations avoid them
What Is a Key Performance Indicator (KPI)?
The most cited definition of a KPI comes from The KPI Institute. The Institute defines a KPI as “a measurable expression for the achievement of a desired level of results in an area relevant to the evaluated entity’s activity.”
Break that down and three things stand out. First, a KPI has to be measurable. Second, it points to a desired result, not just an observation. Third, it only counts if it sits in an area that matters to whoever is being measured, whether that’s a company, a department, a team, or a single employee.
A KPI is not a stand-in for “anything you can count.” Website visits, email opens, or the number of meetings held in a week are data points. They only become KPIs once they connect to a specific objective and someone acts on the result. That connection to strategy is what separates a KPI from ordinary business data, and it’s also the single most common thing organizations get wrong.
KPIs Operate at Multiple Levels
A KPI rarely stands alone. It usually sits inside a chain that runs from the boardroom down to a single desk.
Corporate level: KPIs here back strategic alignment and executive decisions. Think $ Revenue Growth or % Market Share.
Departmental level: KPIs guide functional effectiveness inside a single team, such as % On-Time Delivery in operations or % Retention Rate in HR.
Individual level: Personal KPIs connect one person’s work to the bigger goal, such as # Projects De9/3/2026Slivered On Time for a project manager.
When these three levels are built correctly, a frontline employee can trace a straight line from their own KPI to a strategic objective on the board’s scorecard. That line of sight is one of the clearest signs of a mature performance system, and its absence is one of the clearest signs of a broken one.
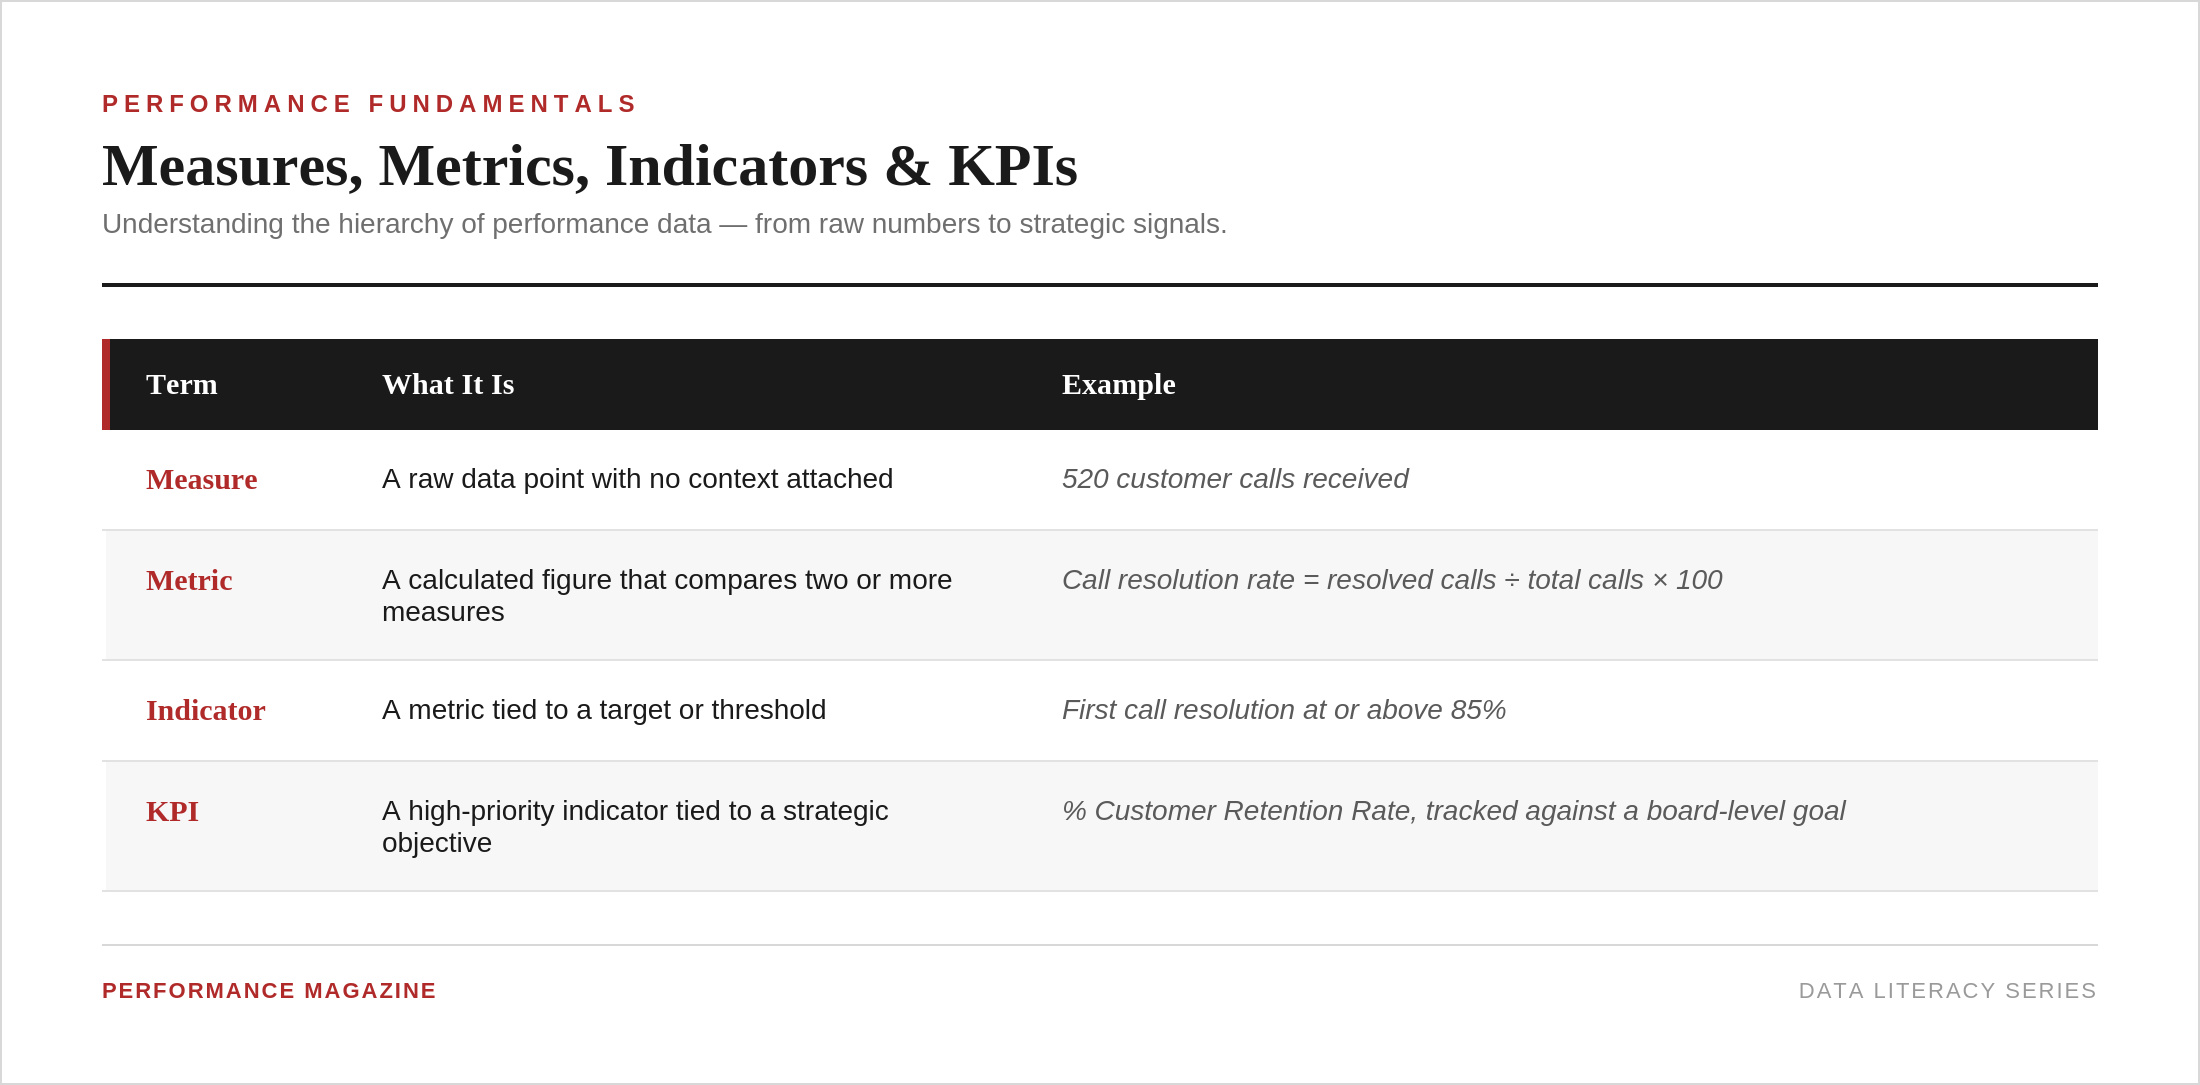
KPI vs. Metric vs. Measure vs. Indicator
These four words get used as if they mean the same thing. They don’t, and mixing them up is one of the fastest ways to end up with a bloated, confusing dashboard.
Data moves up this chain: from raw measure, to metric, to indicator, to KPI. Most organizations track hundreds of metrics. Very few of those metrics deserve KPI status, because a KPI is reserved for the handful of numbers senior leadership actually uses to make decisions.
Where KRAs, PIs, and KRIs Fit In
The KPI Institute’s Body of Knowledge places KPIs inside a wider hierarchy of performance terms. Getting this right matters for anyone building a scorecard or a reporting structure.
Key Result Area (KRA): A broad domain where an organization has to perform well, such as Customer Experience or Operational Efficiency. A KRA is not measurable on its own; it needs indicators underneath it.
Key Performance Indicator (KPI): A high-priority, strategically significant measure tied to a KRA and reported to senior leadership.
Performance Indicator (PI): A supporting measure, relevant at the team or process level but not critical enough to reach the executive scorecard. Think # Daily Orders Processed rather than % Customer Retention Rate.
Key Risk Indicator (KRI): A forward-looking measure that flags a threat before it damages performance. Where a KPI asks “are we hitting our goals,” a KRI asks “what could stop us.”
Together, these terms form a structure that runs from strategic intent down to the data behind a single report. Companies that skip this structure tend to end up with dashboards full of numbers nobody uses.
Why KPIs Matter
A KPI is worth building only if it changes behavior. The KPI Institute’s research points to six areas where well-designed KPIs pay off.
Clarity. A KPI turns a vague ambition like “get better at customer service” into something concrete, such as % First Call Resolution. Teams stop guessing at what success looks like. Example: a retail chain that tracks $ Sales per Square Foot gets a single number that lines up real estate, merchandising, and store operations around one shared measure of location performance.
Focus. With a small set of KPIs in place, attention goes to what actually drives results instead of spreading across everything that can be counted. Example: a hospital that tracks # Average Patient Wait Time channels staff effort into the specific process fixes that shorten delays.
Improvement. A KPI trending in the wrong direction is a prompt for action, whether that means a root-cause review or a new initiative. Example: a software company watching # Issue Resolution Time climb can launch a code review process before customer satisfaction takes the hit.
Engagement. Employees who can see how their daily work moves a KPI tend to feel more ownership over the outcome than employees who only hear about targets secondhand. Example: a call center agent measured on % First Call Resolution understands their effect on customer loyalty, not just call volume.
Communication. KPIs give departments and executives a common language, which cuts down on the back-and-forth that happens when everyone reports numbers differently. Example: an ESG report built around # CO₂ Emissions per Product tells shareholders and customers a consistent story about environmental performance.
Learning. Over time, KPI trends and benchmarks become a record of what worked and what didn’t, and that record is worth more the longer an organization keeps it. Example: a marketing team reviewing a falling $ Cost per Lead across several campaigns can trace which tactics worked and repeat them.
Types of KPIs
KPIs get classified a few different ways, and it helps to know all three.
By timing. Leading indicators predict future performance (# Sales Pipeline Opportunities). Lagging indicators confirm what already happened (% Net Profit Margin). A balanced scorecard needs both, because leading indicators alone can be unreliable, and lagging indicators alone arrive too late to act on.
By scope. Strategic KPIs sit at the corporate level and matter to the board. Operational KPIs track a specific process or team, often on a weekly or monthly cycle, and roll up into the strategic picture.
By format. The KPI Institute’s naming convention tags every KPI with a symbol that signals what kind of number sits behind it:
# (count): # New Clients, # Incidents Resolved
% (rate or proportion): % Customer Satisfaction, % Employee Turnover
$ (monetary figure): $ Revenue per Employee, $ Cost per Unit
This small convention does a lot of work. Anyone who looks at a dashboard can tell at a glance whether they’re looking at a count, a rate, or a dollar figure, without reading the full label.
The Balanced Scorecard: Where Most KPIs Live
Kaplan and Norton introduced the Balanced Scorecard in a1992 Harvard Business Review article as a way to measure performance beyond financial results alone. It groups KPIs into four perspectives:
Financial: Revenue Growth Rate, Net Profit Margin, Return on Investment
Customer: Customer Satisfaction, Net Promoter Score, Customer Retention Rate
Internal Process: Process Cycle Time, Error Rate, Time to Market
People, Learning & Growth: Employee Engagement Score, Training Hours per Employee, Internal Promotion Rate
By 1996 the same framework had already expanded from measurement into strategy execution. Most modern KPI frameworks, including The KPI Institute’s own, still lean on this four-perspective structure because it forces a company to look past the income statement.
How to Write a Good KPI
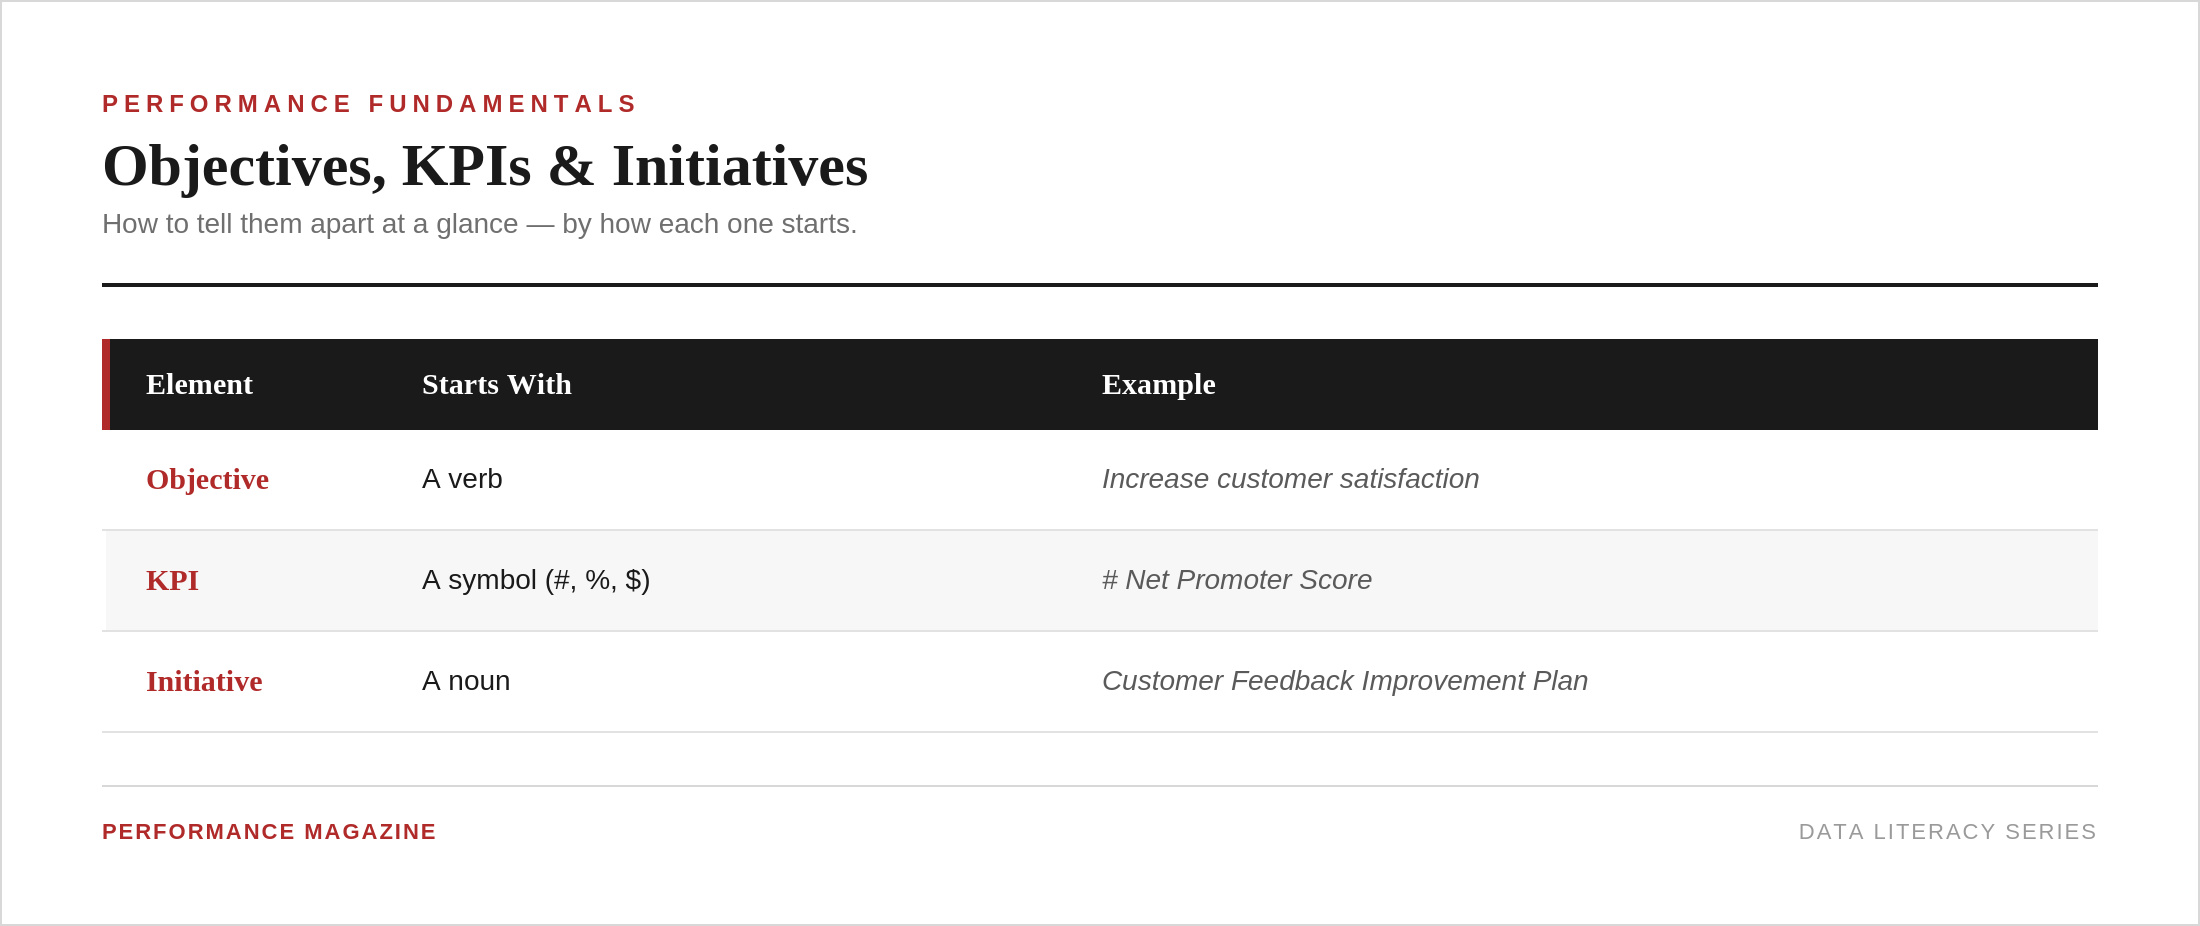
The KPI Institute recommends a consistent naming pattern that keeps objectives, KPIs, and initiatives from blurring together:
Once the objective is set, the KPI itself should meet the SMART test:
Specific: It measures one clear thing, not a vague ambition.
Measurable: The data behind it can be collected consistently.
Achievable: The target is a stretch, not a fantasy.
Relevant: It ties back to a real strategic priority, not a number that’s just easy to pull.
Time-bound: It has a reporting frequency and a deadline attached.
A KPI that fails even one of these tests tends to get ignored within a quarter.
The KPI Lifecycle
KPIs are not set-and-forget. The KPI Institute’s Body of Knowledge describes three stages every KPI moves through:
Establishment. The organization selects the KPI, documents it, and puts data collection in place.
Use. Data flows in on a regular cadence, and the KPI feeds into real decisions and reporting.
Evolution. Over time, a KPI is kept as-is, refreshed to stay relevant, suspended once it stops adding anything useful, or replaced by a more advanced measure. % Customer Satisfaction, for example, is often superseded by # Net Promoter Score as an organization matures.
Many companies skip the evolution stage, and that’s one of the most common mistakes in performance management. Plenty of organizations still track KPIs that made sense five years ago and haven’t been reviewed since.
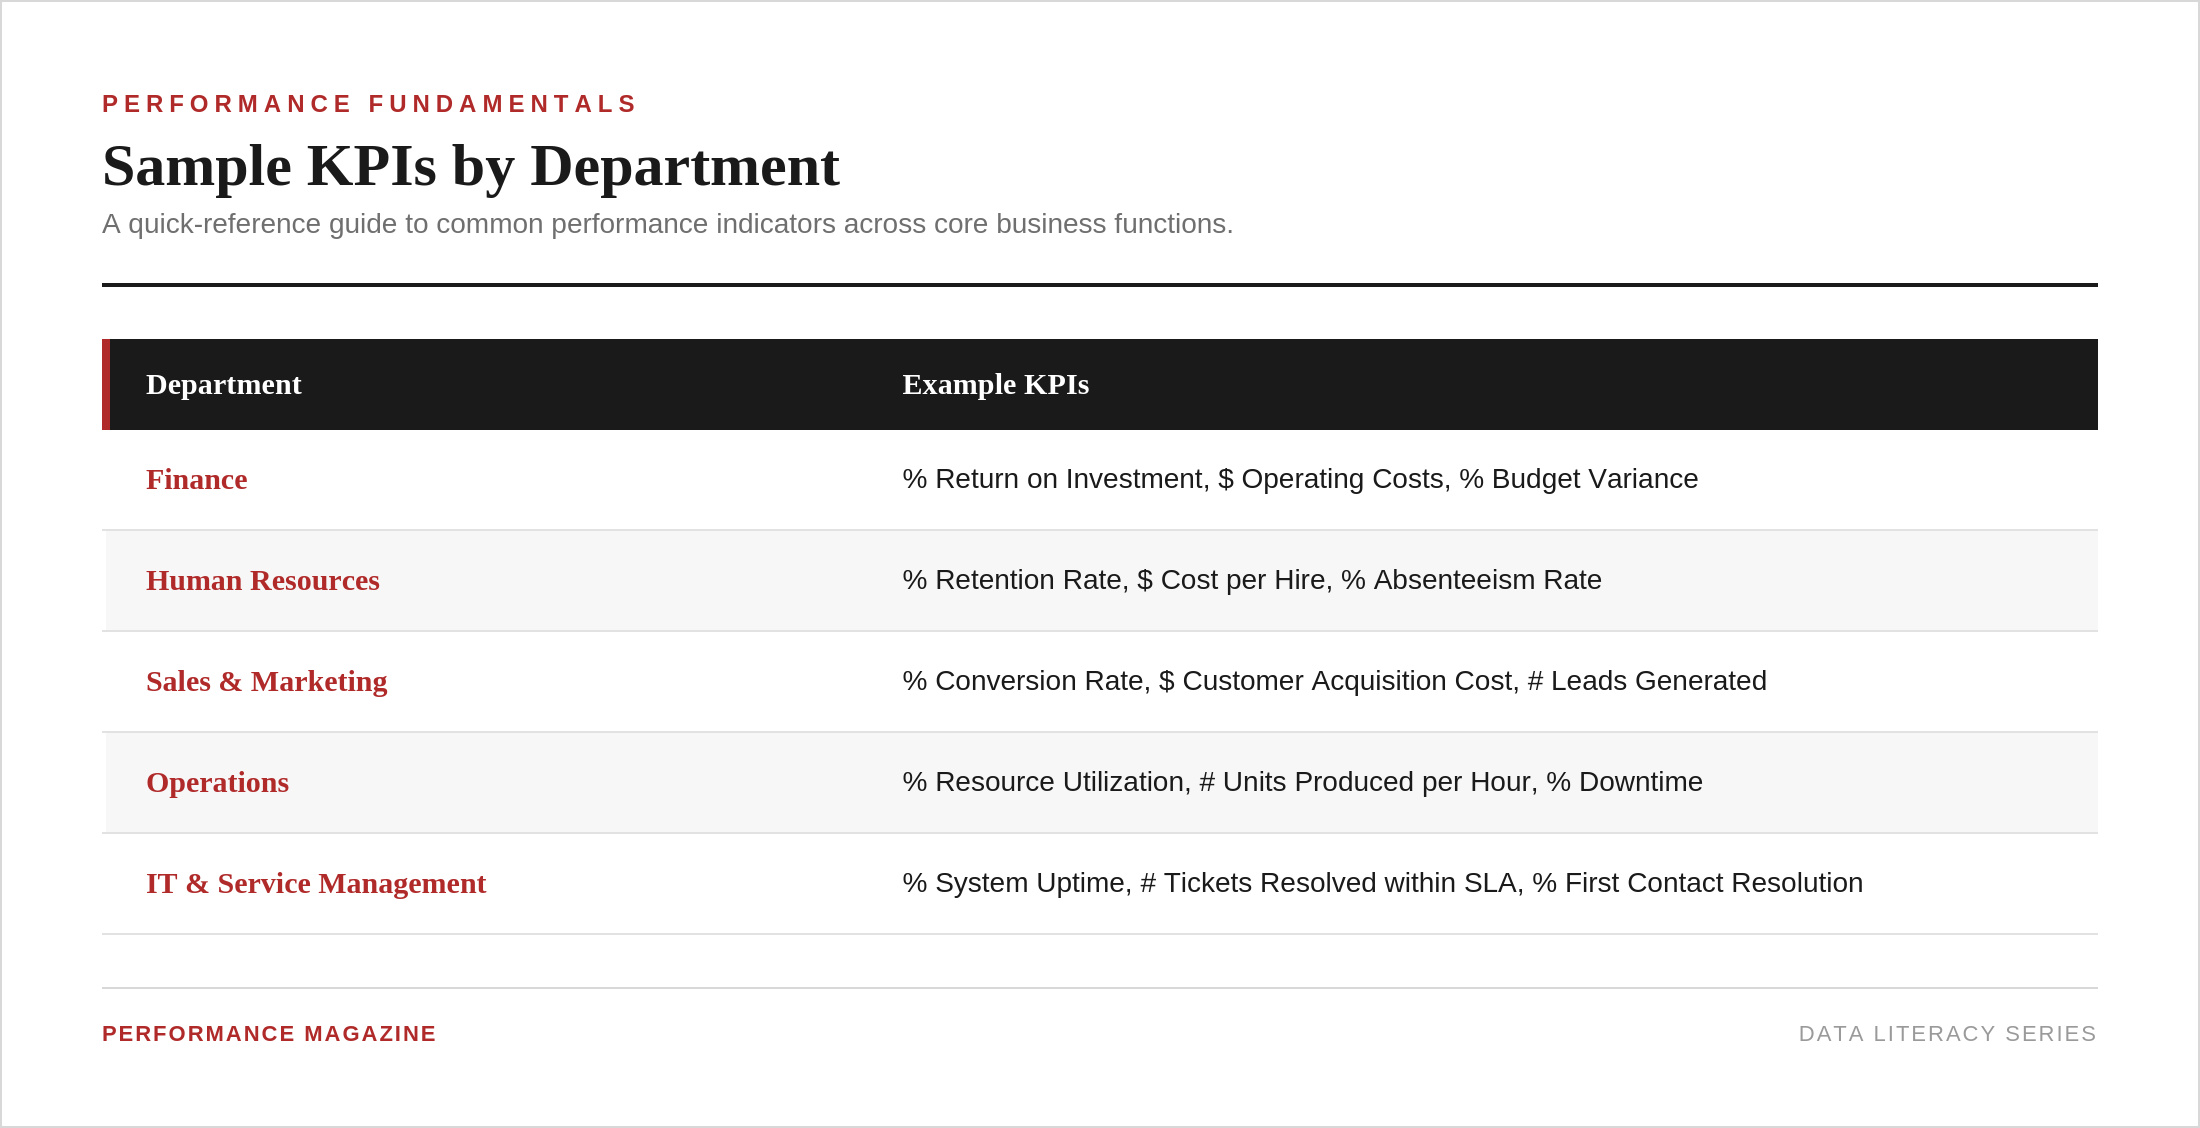
KPI Examples by Department
Most of these work best in combination rather than alone. Tracking # Tasks Completed alongside % Tasks Completed on Time and $ Value Generated per Task gives a fuller read on performance than any single number can.
Performance Measurement vs. Performance Management
These two terms get treated as synonyms, and they shouldn’t be. Neely et al. (1995) define a performance measurement system as a set of metrics used to quantify the efficiency and effectiveness of actions. Forza and Salvador (2000) go further, describing it as an information system that supports two functions: structuring communication around target setting, and collecting, processing, and delivering data on how people, processes, and business units are performing.
Performance measurement deals with the evaluation of results. Performance management deals with what happens next: the decisions, initiatives, and behavior changes built on top of that evaluation. One tracks the score. The other decides what to do about it.
The Balanced Scorecard is a good illustration of how the two ideas merge over time. Kaplan and Norton introduced it as a measurement tool in 1992. By 1996 it had grown into a strategic management system. By 2008 it sat inside a wider system for planning, execution, and organizational learning. A tool built to measure performance turned, over 16 years, into a system built to manage it.
Common KPI Mistakes
A few problems show up in nearly every organization that struggles with KPIs:
Measuring everything. Dashboards that carry 40 metrics dilute attention instead of sharpening it. A KPI list should be short enough that people remember it without looking it up.
Skipping alignment. When department KPIs aren’t linked to corporate objectives, teams end up optimizing for numbers that don’t move the business forward as a whole.
Weak documentation. A KPI without a documented formula, data source, owner, and reporting frequency is open to different interpretations by different people, and that alone can undermine trust in the number.
Stale data. A KPI that shows up weeks after the fact turns into a post-mortem rather than a tool for a live decision.
No data governance. Someone has to own data quality for each KPI, from the source system down to how often it gets refreshed. Without a named data custodian, small errors in a spreadsheet quietly turn into board-level decisions built on bad numbers.
Most of these mistakes trace back to the same root cause: a KPI system built around what’s easy to pull from an existing report, rather than what the organization actually needs to know.
Frequently Asked Questions
What does KPI stand for? KPI stands for Key Performance Indicator: a measurable value linked to a specific strategic or operational objective.
What is the difference between a KPI and a metric? A metric is any calculated figure built from raw data. A KPI is a small subset of metrics selected because it ties directly to a strategic goal and gets used by decision-makers. Every KPI is a metric, but not every metric is a KPI.
How many KPIs should an organization track? There’s no fixed number, but most performance management practitioners recommend keeping the list short, often somewhere between five and fifteen at the corporate level. More than that and the system tends to lose focus.
What makes a good KPI? A good KPI is specific, measurable, tied to a real objective, and something the organization can act on. If a KPI can’t change a decision, it’s not doing its job.
Is revenue a KPI? Revenue can be a KPI if it’s tied to a specific strategic target, such as $ Revenue Growth against a year-end goal. Without a target or an owner, it’s closer to a raw financial metric.
Who is responsible for setting KPIs in an organization? Top management sets the strategic direction and signs off on major KPIs, but the day-to-day design usually sits with a strategy or performance office, and department heads take ownership of the KPIs specific to their teams.
What is the difference between a KPI and a KRI? A KPI tracks progress toward a goal. A Key Risk Indicator (KRI) tracks the likelihood of something going wrong before it happens. Mature performance systems track both side by side.
What is the difference between a leading and a lagging KPI? A leading KPI predicts future performance, such as # Sales Pipeline Opportunities. A lagging KPI confirms a result that already happened, such as % Net Profit Margin. Leading indicators give teams time to act; lagging indicators tell them whether that action worked.
Can a KPI change over time? Yes, and it usually should. The KPI lifecycle covers exactly this: a KPI gets maintained while it’s still relevant, refreshed when its calculation needs adjusting, suspended once it stops adding anything useful, or replaced by a more advanced measure as an organization matures.
What is the difference between a KRA and a KPI? A Key Result Area (KRA) is a broad domain, such as Customer Experience or Financial Performance. It isn’t measurable by itself. A KPI is the specific, quantifiable measure placed underneath a KRA to track progress inside that domain.
Where to Go From Here
For a deeper look at any single part of KPI management, from documentation templates to lifecycle management to industry-specific examples, see:
How Can You Improve the Data Gathering Process for Your KPIs? – “An important component of performance measurement is represented by the data collection capability. However, when applied in the organizational context, this process is neither easy nor lacking obstacles, as practitioners often discover.”
How Can We Ensure Our KPIs Are Aligned With the Strategy? – “In many cases, the key performance indicators (KPIs) monitored do not seem relevant as they are not connected to the strategy. To better understand how this problem can be addressed, we must first identify its possible causes.”
How to Implement a KPI Measurement Framework – “A KPI implementation project plan provides a structure for the implementation of an organization’s performance management system. Once the project plan is set, all types of activities would have a clear deadline and designated responsibilities.”
Project Plan: Developing a Performance Management System Based on KPIs – “When formalizing and implementing a performance management system (PMS) based on key performance indicators (KPIs), there are multiple activities to be considered and many stakeholders to be engaged in the process. Therefore, you’ll need a project plan to make performance management an ongoing process within your organization.”
[Watch] KPI Selection Techniques – “Learn how KPI selection techniques can be implemented in practice and gain insights into the best practices for selecting KPIs.”
Advice on KPI Selection – “KPI selection is a process which seems simple, yet is inherently complex, due to the interdependencies involved. Here are 15 things to consider before embarking on this journey.”
[Watch] Overcoming KPI Selection Challenges: Applying KPI Selection Techniques – “What are the most important guidelines to follow when selecting KPIs for strategic objectives? What are the most efficient KPI Selection techniques, most recommended KPI selection environments, and some Value Flow Analysis technique examples?”
KPIs are not just about understanding and working with numbers. Using KPIs requires stakeholders to fulfill a vision and commit to ensuring success across all levels of their organization. If you would like to learn how to select the right KPIs for your organization, sign up for The KPI Institute’s Certified KPI Professional and Practitioner live online course today.
*********
Editor’s Note: This guide draws on The KPI Institute’s more than 20 years of research, expertise, and practical experience in performance management. Its core definitions, terminology, and frameworks are grounded in the Institute’s forthcoming KPI Body of Knowledge, developed under the leadership of Marcela Presecan, Head of Research at The KPI Institute.
The balanced scorecard (BSC) is a widely used performance measurement framework for strategic planning. It is so popular, in fact, that The KPI Institute’s latest State of Strategy Management Practice report found that 40% of respondents from Middle Eastern companies were using it. Why is that the case? It’s likely in the name—the BSC offers a balanced perspective of a company’s performance, focusing not just on financial gains but the various aspects of value creation as well. This enables companies who use it to establish sustainable business practices that can meet long-term goals without sacrificing short-term improvements.
What Is the BSC?
In 1992, Robert Kaplan and David Norton dreamed of a better way. Aware of the limitations of traditional practices that focused solely on financial indicators such as return on investment (ROI) to measure a company’s performance, the two designed a tool that incorporated non-financial variables to paint a more holistic, comprehensive picture. Thus, the balanced scorecard was born.
The BSC was further refined by connecting performance metrics directly to strategy, which marked a formal link between strategic goals and performance measurement. In 1996, it became a performance management system (PMS) that effectively integrated the various crucial aspects of an organization—i.e. strategic processes, resource allocation, budgeting and planning, goal setting, and employee learning.
By 2001, the BSC had outgrown its original form, no longer seen as a mere management tool but instead as an all-encompassing strategic management and control system. The BSC has continued to evolve alongside the ever-changing priorities of the business world. In 2021, many companies began integrating environmental and social dimensions into their BSCs to reflect their triple bottom line strategies.
The BSC gives managers a view of the business from four crucial perspectives. Each perspective deals with an integral aspect of the organization and answers a specific question:
Customer Perspective: How Do Customers See Us?
Companies typically have a mission statement that encapsulates how they interact with customers. For example, e-commerce platform Etsy’s mission statement is “Keep Commerce Human.” This sentiment informs the way the company does business, which places importance on leaving a positive economic, social, and ecological impact.
The BSC holds companies accountable to their mission statements by translating them into specific measures that must be followed. For Etsy, one aspect to consider would be the diversity of its workforce, which falls under social impact. To address this, the company has taken measures such as increasing the presence of underrepresented communities in its seller community by interviewing candidates from those backgrounds. This has enabled the company to stay true to its mission and show customers that it walks the talk.
Internal Perspective: What Must We Excel At?
Balance is the primary focus of the BSC—it’s in the name, after all. Thus, the framework doesn’t only take into account the way customers perceive the company, but it also considers what the latter does to shape this perception. This is composed of the various operational and organizational processes that drive the company.
By giving managers an internal perspective, they can identify, track, and measure the processes that yield the most benefits and close the gaps on the ones that fall short.
Learning and Growth Perspective: Can We Continue to Improve and Create Value?
The business landscape is constantly shifting, and in order to keep pace with its changes, businesses must consistently learn and innovate. That is the importance of this perspective, which states that a company’s value hinges on its ability to improve. In any industry, competition can be fierce, which means companies must always find new ways to stand out.
Financial Perspective: How Do We Look to Shareholders?
Among the four perspectives, this is perhaps the most straightforward. Put simply, it indicates if a company is profitable. Although financial performance is no longer the end-all, be-all measure of a company’s success, it still plays a crucial role in determining whether a company is simply surviving or thriving. Shareholders understandably value profitability, and they won’t keep investing in a company that doesn’t produce ROI.
The BSC is by nature a holistic framework, meaning each part is interconnected to the others. This is why it’s important to take a balanced (pun intended) approach when considering the four perspectives. If one side is prioritized over the others, it could lead to the formation or widening of inefficiency gaps that impede business growth and success.
As previously mentioned, the BSC is quite popular. This is due to the myriad of benefits that it brings to organizations that use it wisely. The most obvious benefits of the BSC are twofold. First, it consolidates the seemingly disparate aspects of a business in a single report, leading to increased efficiency in performance reporting and measurement as well as faster decision-making. Second, the BSC helps mitigate suboptimization by making managers consider the entirety of the company’s operational measures, demonstrating whether one objective was achieved at the cost of another.
A more concrete example of the BSC benefiting companies can be seen in how Apple uses the framework. By shifting its focus from innovating its products to also paying mind to customer satisfaction by establishing it as one of the company’s core tenets, the tech giant was able to improve its already stellar reputation by catering to its customers’ desires. Apple also values core competencies, employee commitment and alignment, market share, and shareholder value. Together, these indicators make up the metrics of their BSC.
World-renowned electronic company Philips is also known for its use of the BSC, using a bespoke version of the framework to fit its organizational needs. The company’s focus is on its employees, and it uses the BSC to ensure that each member of its workforce has a clear understanding of the company’s strategic policies and long-term vision.
What Does the Future Hold?
There must be a stronger emphasis on customization as companies realize that there is no such thing as a one-size-fits-all approach to performance management. This aligns with the proliferation of new advancements in artificial intelligence (AI) and machine learning (ML), technologies that must be integrated into the BSC lest the framework fall behind the ever-shifting realities of the business world. Regardless of the future, the BSC appears poised to remain a vital tool for companies of all sizes and in all industries.
Interested in learning more about the BSC? Browse our articles here.
In an era when environmental concerns are at the forefront of global discussions, businesses are being called upon to integrate sustainability into their operations. Developed as an extension of the traditional Balanced Scorecard (BSC), the Sustainability Balanced Scorecard (SBSC) aims to provide businesses with a tool to align their environmental, social, and economic objectives, driving positive impact while ensuring long-term success.
The genesis of the SBSC
The concept of the BSC was first introduced by Robert Kaplan and David Norton in the early 1990s as a framework to measure business performance beyond financial metrics. The BSC aimed to provide a more holistic view of an organization’s health by incorporating four hierarchical perspectives: Financial, Customer, Internal Processes, and Learning & Growth.
A decade later, as sustainability became a critical global concern, scholars started looking into the possibility of integrating sustainability considerations into the BSC. They agreed on the potential of extending the focus of the well-established BSC to include measuring business performance through the lens of environmental stewardship, social responsibility, and ethics. Thus, the concept of the SBSC began to crystallize .
How to build an SBSC
When it comes to the best architecture for the SBSC, there have been conflicting discussions ever since the concept was introduced. Two major approaches took prominence: one is to add a fifth perspective to the traditional BSC that was dedicated to sustainability; the other is to integrate sustainability objectives and KPIs into the already existing perspectives.
A 2009 study showed that in the fifth perspective approach, sustainability KPIs tend to be overlooked by management in organizations with no established sustainability culture. That is why the four-perspective approach can be a safer choice, especially for organizations that are only starting to integrate sustainability in their measures.
In a 2021 article, Kaplan supported the four-perspective approach, introducing a suggested restructuring of three out of the four perspectives to make them more relevant to environmental, social, and governance (ESG) elements:
From “Financial” to “Outcomes” to include environmental and societal objectives besides the financial aspect
From “Customer” to “Stakeholder” to reflect the value of different members of the whole ecosystem
From “Learning & Growth” to “Enablers” to encompass the various capabilities across all stakeholders in the ecosystem
Reaping these sustainability integration benefits can be a bit of a long shot, and further studies are needed to prove such benefits even exist. However, the only way to reap said benefits is to plant the seeds of sustainability integration. To help accomplish this, the SBSC can be a potent tool that allows organizations to measure, manage, and optimize their sustainability performance. As global challenges such as climate change, resource depletion, and social inequality loom larger, businesses must go beyond profits and consider their broader impact. The SBSC empowers organizations to embrace sustainability as a strategic imperative, paving the way for a more responsible, resilient, and prosperous future.
For more on utilizing the Balanced Scorecard, The KPI Institute has developed the Certified Balanced Scorecard Management System Professional to help organizations maximize the tools’ potential. And if you are interested in expanding your toolkit further, consider subscribing to smartkpis.com and gain access to the world’s largest database of documented KPIs, which includes a thorough collection of sustainability metrics.
Often than not, several executives take strategy as a routine task or a series of frameworks instead of a mode of visualizing and solving problems. Furthermore, taking on the newest strategy trends or following a successful entrepreneur’s guidelines is not an ideal way to win. Companies need to take their strategies through a series of tests to determine their validity.
There are three tests that identify the success of strategies. These assessments help executive teams to answer some of their burning question, such as:
a) Does your company strategy respond to uncertainty and trends?
b) Does your strategy exploit legitimate sources of advantage?
c) Is your strategy aligned and cascaded throughout your organization?
Three Winning Strategy Tests
There are three types of tests companies can apply to determine whether their strategies are viable or not. The first one is the Fit Test. This type of test measures the level of fitness of a company’s strategy along with its business condition. When conducting the Fit Test, there are three fit dimensions that need to be assessed: internal fit, external fit, and dynamic fit.
Internal fit and external fitare the keys to securing a company’s survival (Tyge Payne et al., 2015). Internal fit is described as a multi-dimensional matching of strategy with structure. It is undertaken to ensure that the strategy matches the company’s resources as well as competitive capabilities. Winning strategies display an internal fit and must be compatible with the ability of a company to implement the strategy in a competent mode.
External fit refers to the congruence between an entity’s strategy and composition and its task environment. Testing external fit will exhibit how a strategy matches significantly with the external conditions, such as industry dynamics, competition, and market opportunities. Therefore, a strategy will only work well if it has an excellent external fit against the external environment.
The last type of fit test is dynamic fit. It is a fundamental measurement that assesses if strategies are changing over time. Dynamic fit is used to synchronize and align the current state of the business with market conditions.
According to Jonathan Trevor and Barry Varcoe, retaining a good strategic alignment relies on the ability of a company’s structure, procedures, and culture to evolve with strategy changes. The signs of misalignments are always evident to employees and customers who fail to receive the type of service they expect.
The second type of test is called the Competitive Advantage Test. This type of test measures the lasting competitive advantages of businesses in the market space. The Competitive Advantage Test also enlightens managers on strategies that often fail to keep up a constant competitive advantage with rivals. Failed approaches to maintain a competitive advantage over competitors usually lead to inferior performance in the long run.
As winning strategies enable competitive advantage to be durable and larger, the research of competitive advantages in the tech industry by (Huang et al., 2015) sheds light on the outcome differences between Temporary Competitive Advantage (TCA) and Sustainable Competitive Advantage (SCA).
The paper suggests that companies can achieve higher outcomes through SCA by amassing assets, resources, and capabilities. However, TCA created through strengthening market positions can assist firms with capital to accumulate resources that will develop a sustainable competitive advantage.
The Performance Test is the third form of measurement to differentiate a winning or losing strategy. A performance test is vital for organizations as companies usually mark their success based on performance. There are two types of indicators that a company looks at to understand the standard of this strategy test:
a) Competitive strength and market positioning and
b) Profitability and financial strength.
One of the performance measurements tools that businesses can use to effectively manage organizational performance is the balanced scorecard. It provides a holistic strategy implementation framework comprising five elements: desired state of evolution, strategy map, performance scorecard, performance dashboard, and portfolio of initiatives.
To sum it up, a company’s strategy needs to excel in all tests to succeed. Failing in even one of the tests could spell problems for business ventures and lead to negative performance. A company can introduce new practices only if they match or erase both internal and external conditions. On the other side, existing strategies should always be evaluated thoroughly to affirm that they are fit and contribute to good performances and competitive advantage. Incorporate fast changes to current strategies if companies fail at least one of the three tests.
Take a look at The KPI Institute’s website and find out more about the Certified Balanced Scorecard Management System Professional course. Discover new approaches on how to create a performance management system based on the balanced scorecard technique and how to implement it at all levels of the organization.